image_1753096957280.webp

June 2, 2025

I’ll be blunt and direct — there’s no room for comforting illusions when it comes to export growth. The world thrives on exports. This isn’t new, and it’s not up for debate. So, let’s begin with the first consensus: exports are essential for economic survival.

The second consensus is clear: textiles are the backbone of Pakistan’s industrial economy. They’ve long driven growth, jobs, and foreign exchange — but that foundation is now weakening in the absence of sustained policy support needed to remain globally competitive.

Here’s the third and perhaps most urgent consensus: if exports are vital — and textiles are their engine — then supporting this industry isn’t optional. It must be treated as a national economic priority, not something to be strangled by misguided policies.

Yet Pakistan’s largest exporting sector is under siege by its own policymakers. While other countries are racing toward industrialisation, we are sliding into premature deindustrialisation. Why? Because Pakistan hasn’t even begun to prioritize export growth and instead treats its most valuable export sector with neglect — and at times, outright hostility.

The consequences are visible. The textile industry is unraveling, and the numbers speak for themselves. Textile exports fell 14.6% month-on-month in April 2025 and 1.4% year-on-year. Net textile exports dropped from USD 14.08 billion in FY2024 to USD 13.6 billion in FY2025, as imports of cotton, yarn, and greige fabric surged from USD 2.1 billion to USD 3.6 billion.

Since the irrational tax measures of Budget 2024, over 120 spinning mills have shut down, with many others operating below 50% capacity. Millions of jobs have been lost. More and more skilled labour is leaving the country as large-scale manufacturing is in retreat, with output shrinking 1.9% during July–February FY2025, compared to a 0.4% contraction last year.

With over 55% of our total exports stemming from textiles, the sector’s strategic importance should be unquestionable. Yet it is being treated as expendable.

Policymakers may speak of “reforms,” but any policy that undermines exports is not reform — it is a strategic blunder. The widening gap between rhetoric and reality is pushing the sector to the brink. The problems are well known, but they must be stated again — clearly, urgently, and without euphemism.

Energy is the sector’s most urgent crisis – no export industry can survive without reliable, affordable supply. At the core of the textile industry’s collapse is a deliberate pricing-out through inconsistent and inflated energy costs. While competitors like Bangladesh, India, and China offer gas at $6–9/MMBtu and electricity at 5–9 cents/kWh, Pakistan continues down a regressive, irrational path.

Since July 2023, the gas/RLNG tariff for captive use has surged from Rs. 2,364/MMBtu to Rs. 3,500/MMBtu. On top of that, a Grid Transition Levy of Rs. 791/MMBtu raises the effective captive gas price to Rs. 4,291/MMBtu -approximately $15.38/MMBtu – nearly double what our competitors pay. Even worse, this levy is calculated based on the B-3 peak rate, which applies for only four hours a day.

This isn’t a miscalculation – it’s an intentional policy choke. CPPs – once encouraged to fix load-shedding – are now being penalized just to spread the grid’s inefficiency costs across more users.

But switching to the grid offers no respite. Electricity tariffs in Pakistan are the highest in the region—12–14 cents/kWh compared to 5–9 cents/kWh elsewhere. The grid itself is unreliable, plagued by outages, stranded costs, and circular debt. Exporters face a brutal dilemma: either pay exorbitantly for unreliable power and lose competitiveness, or halt production and go out of business.

This is far from a free market where exporters cannot even choose their own energy inputs. What we’re witnessing isn’t just a distortion— it’s a deep, systemic policy failure.

Then there’s another policy absurdity: regressive taxation, one of the great ironies of Pakistan’s tax system, treating exporters more like easy tax targets than growth drivers. The FY2025 budget pushed exporters into the normal tax regime, imposing a 1.25% advance minimum turnover tax adjustable against a 29% income tax, alongside a super tax of up to 10%.

With that, exporters also face a 1.25% advance tax on export proceeds and a 0.25% export development surcharge – pushing their total tax burden up to135%. This is not only punitive but also blatantly discriminatory. Extensive research shows that such regressive taxes encourage evasion while stifling investment and growth. Textile firms, already operating on razor-thin margins, are now squeezed on liquidity, with the turnover-based tax alone drastically hampering cash flow and production capacity.

Compounding the crisis, FY2025 policies have crippled domestic suppliers. The Export Facilitation Scheme previously allowed duty- and sales-tax-free access to all inputs, but the government withdrew the sales tax exemption on local supplies for export manufacturing—while imported inputs remain zero-rated.

Ten months into this policy, the consequences are severe. Over 120 spinning mills have shut down, and associated industries are nearing collapse. Exporters are increasingly turning to imported yarn, whose value has surged by 225% in just three quarters—from USD 142 million to USD 462 million.

This isn’t just hurting our trade balance. Every day this policy remains in place, factories shut down and unemployment grows. Deindustrializing the spinning sector risks losing over $15 billion in sunk investment, in addition to the investment made under TERF.

Worsening the situation, the sales tax on domestic procurement is choking liquidity and halting production. Although refundable in theory, only 60–70% of sales tax refunds are paid—and with delays over six months. The FASTER system, which promised 72-hour automated refunds, is now defunct. Manual refunds have made no progress in four years. Working capital has dried up.

“Here’s the staggering reality: as of FY2024, the government owes the textile sector Rs. 55 billion in sales tax refunds, Rs. 105 billion in deferred sales tax, Rs. 25 billion in duty drawbacks, Rs. 100 billion in income tax refunds, Rs. 35.5 billion in DLTL/DDT dues, Rs. 4.5 billion in TUF payments, Rs. 3.5 billion in markup subsidies, and Rs. 1 billion in RCET differentials. All these funds remain stuck. Exporters aren’t asking for subsidies—only timely refunds of their own money to reinvest.”


But the state seems dependent on private sector liquidity to manage its fiscal distress.

Policies in Pakistan shift in the blink of an eye. Just rewind a few years. Between 2020 and 2022, the textile sector saw a rare surge, fueled by the TERF scheme, competitive energy tariffs, and strong post-COVID demand. Capacity grew across spinning, weaving, dyeing, and garmenting. But by 2023, this momentum collapsed—not due to global demand, but inconsistent and hostile domestic policies. Nearly 30% of capacity now lies idle, expansion plans seem elusive, and firms are either investing in non-tradables or considering relocation.

This must change immediately.

Today, amid Trump tariffs reshaping the global order, markets are starting to see potential in Pakistan over regional rivals. The USA has recently extended trade ties, and the now-cancelled Pak-EU Business Forum 2025 sparked hope for more trade and investment. But how can new capital come in when current businesses are struggling to survive?

In short, exports are declining and FDI has dried up. The government’s primary sources of dollar inflows are remittances—which, over time, suppress exports, drive up consumption and imports, and hinder growth—or external debt. But where is the sustainable dollar inflow from exports?

No matter how many URAAN plans are rolled out, without fundamental policy shifts, exports won’t recover.

And to achieve export-led growth, the government must recognize that the way forward begins with energy. Power tariffs need to be regionally competitive – capped at 9 cents/kWh – to restore cost parity. The cross-subsidy system, which unfairly burdens industry, must be abolished. A uniform tariff should replace the existing Time-of-Use system.

Exporters should be empowered to procure power directly via B2B contracts by implementing CTBCM or similar frameworks. Gas pricing must align with industrial realities. Co-generation users should be reclassified under industrial process tariffs. The flawed Grid Transition Levy requires transparent recalculation. Additionally, exporters must have the right to procure domestic gas or import LNG independently through Third Party Access.

With that, the EFS must also be revised. Ideally, zero-rating of local supplies should be restored to the June 2024 framework. If IMF constraints prevent this, implementing a negative list of EFS imports—including yarns and fabrics—is the only viable way forward to ensure a level playing field.

Corporate taxation needs immediate rationalization. The 1% advance tax on export proceeds, layered on top of income tax, constitutes double taxation and should be abolished. Pakistan must adopt a graduated sales tax system like India’s, where raw materials are taxed at lower rates than finished goods. This will improve tax compliance, curb evasion, and strengthen competitiveness.

Also, refund delays must be fixed immediately. The government should release all outstanding dues to exporters and restore their working capital to revive exports.

Most importantly, every policy must be based on clear cost-benefit analysis, which is currently missing, causing conflict and chaos. The Planning Ministry pushes the $50 billion URAAN package, while FBR focuses on irrational, anti-business taxes over industrial growth. Finance Ministry claims to seek sustainable dollar inflow but approves regressive taxes and gas levies that choke the industries meant to generate it.

While the world races ahead with traceability, ESG standards, and digital certification, Pakistan is pushing itself out of global value chains through inconsistent, anti-export policies. We’re not just falling behind—we’re cutting ourselves off. The math is clear: export growth means jobs, dollars, and stability; export decline means debt, IMF bailouts, and rising unemployment. It’s high time the government shifts focus away from remittances and bailouts – and commits fully to export-led growth.

There is no room for illusions anymore; the government must face reality and act


image_1752834846044-1280x853.webp

May 21, 2025

By Shahid Sattar | Sarah Javaid
The EU’s Carbon Border Adjustment Mechanism (CBAM) is now a pressing challenge for exporters worldwide. By pricing the carbon content of imports, CBAM ensures companies outside the EU face the same climate costs as European manufacturers under the EU Emissions Trading System (ETS). It is a key part of the EU’s goal to be carbon neutral by 2050, preventing “carbon leakage” ensuring that all carbon emissions – regardless of origin – are equally penalized.

In its first phase (2023–2025), the CBAM targets high-carbon sectors such as iron, steel, cement, aluminum, and fertilizers. However, from 2030 onwards, textiles are expected to be included, posing serious implications for textile manufacturing countries.

While textiles are not as energy-intensive as the sectors currently covered under CBAM, the policy could still undermine Pakistan’s export competitiveness given the dependency on textile export revenue.

With the EU as Pakistan’s largest export market and textiles as its major export, future market access will increasingly depend on the carbon footprint of Pakistani goods. Given the price-sensitivity and highly elastic nature of textiles, even marginal cost increases from carbon tariffs could lead to a noticeable drop in demand.

For Pakistan, the risk of losing competitiveness is especially urgent due to three interrelated structural challenges in its industrial sector.

First, industrial emissions in Pakistan have steadily risen over the past five decades, driven by a growing reliance on coal. This shift could make the country’s manufacturing base increasingly carbon-intensive and less competitive in a climate-conscious global market.

Second, Pakistan is a net importer of carbon emissions – an often overlooked aspect of its climate profile. The carbon embedded in imported raw materials and intermediate goods adds to the emissions footprint of its export value chains, inflating the overall carbon intensity of its final products.

Third, recent energy reforms – such as the gas levy and the proposed CPP levy legislation under IMF conditionalities – appear designed to push industries away from cleaner, gas-based self-generation toward the more carbon-heavy national grid, risking an increase in emissions per unit of output.

Together, these trends not only raise Pakistan’s exposure to CBAM-related costs but also risk non-compliance with international climate obligations under the UNFCCC, the Paris Agreement, and Sustainable Development Goals (particularly SDG 7 on clean energy and SDG 13 on climate action).

In an era where climate standards are becoming a precondition for access to global markets, Pakistan’s energy trajectory – marked by rising emissions, imported carbon, and coal reliance – could undermine its export competitiveness and expose it to carbon and trade penalties if left unaddressed.

Coal reliance and accelerating carbon emissions in Pakistan:

Pakistan’s emissions profile underscores the urgent challenge ahead. Coal power, which accounts for 40% of the country’s energy mix, is a significant contributor to rising emissions. Despite its environmental costs, Pakistan remains heavily reliant on coal imports due to its low cost and CPEC-linked investments that have deepened this dependence.

However, this reliance clashes with the global shift toward carbon accountability. Over the past five decades, carbon emissions from industrial processes in Pakistan have increased at an average annual rate of 5.3%, signaling not only sustained but accelerating carbon intensity in domestic production (see figure 1).

Pakistan as a net importer of carbon:

Importantly, Pakistan’s carbon challenge extends beyond domestic emissions. As a net carbon importer, much of the emissions embedded in its exports come from imported raw materials and machinery, particularly from high-emission economies like China (figure 2). This outsourced carbon, combined with rising local emissions, could make Pakistan’s supply chains carbon intensive – a situation that should be avoided at all costs.

Since CBAM taxes emissions across the production process, Pakistan’s status as a net carbon importer heightens the vulnerability of its exports. In contrast, regional competitors like Vietnam, China, and India are net carbon exporters (figure 3), shifting their emissions abroad. For instance, Zhang and Chen (2022) find that over 6% of China’s exports contain carbon transferred to other Belt & Road Initiative countries, most of which are net carbon importers. Pakistan’s growing reliance on Chinese inputs raises the embedded emissions in its textile exports – thereby potentially eroding Pakistan’s price competitiveness in major markets.

Policy paralysis:

Recent IMF-backed energy reforms further compound this challenge. At the center is the CPP levy, which taxes gas supplied to industrial captive power plants (CPPs) and is set to rise incrementally to 20% by August 2026, over and above grid parity.

Intended to shift industrial demand to the national grid, this policy has unintended climate consequences. By making gas costlier, it pushes manufacturers toward cheaper but dirtier fuels – primarily coal – undermining Pakistan’s climate targets and increasing emissions per unit of output just as global buyers tighten carbon-related standards.

While this levy may force some additional units to shift to the grid, its overall impact remains marginal, as gas/RLNG consumption has already declined by 75% due to prohibitively high OGRA-notified prices.

The long-term costs are steeper: elevated emissions, rising industrial energy costs, and greater exposure to carbon border taxes. With more trading partners adopting carbon accountability frameworks, Pakistan stands to lose billions in export revenues unless it aligns its industrial energy policy with global climate goals. While the IMF has recently proposed a domestic carbon levy for Pakistan, the detailed framework is yet to be developed.

Potential violation of international conventions:

The implications extend beyond trade and competitiveness. Increased coal use driven by distorted energy pricing risks violating Pakistan’s international commitments.

As a signatory to the United Nations Framework Convention on Climate Change (UNFCCC), and the Paris Agreement, Pakistan is obligated to reduce emissions by 20% by 2030 and transparently report its progress. Increased reliance on coal will spike carbon emissions, drawing international scrutiny and weakening Pakistan’s credibility in climate negotiations. It also risks non-compliance with the EU’s GSP+ scheme, where upcoming monitoring missions – such as the one expected in June – assess adherence to environmental commitments.

More broadly, continued coal dependency clashes with the global shift toward Environmental, Social, and Governance (ESG) standards under WTO frameworks, increasing the risk of non-tariff barriers and reduced market access. It also undermines Pakistan’s progress toward Sustainable Development Goals—particularly SDG 7 (Affordable and Clean Energy) and SDG 13 (Climate Action) – and threatens the country’s broader 2030 development agenda.

CHPs for industrial decarbonization:

To avoid the rising costs of carbon non-compliance and trade penalties, Pakistan must urgently reorient its industrial energy strategy. The path forward lies in smartly integrating renewable energy with gas-based Combined Heat and Power (CHP) systems. CHP offers a low-carbon, flexible solution capable of stabilizing the intermittency of renewables like solar, while leveraging existing gas infrastructure.

Additionally, CHP engines can be integrated with solar PV and battery energy storage systems (BESS), creating a practical and scalable route to decarbonize industrial energy use while reducing dependence on imported coal.

These systems also extract maximum economic value from gas molecules by simultaneously generating electricity and useful heat.

In this context, gas and RLNG emerge as essential bridge fuels – classified as cleaner technologies – that can complement renewables and enable the transition to a low-carbon industrial base. Aligning with this strategy not only supports compliance with CBAM but also helps uphold Pakistan’s international climate commitments by lowering industrial emissions.

When reforms backfire:

However, while the need for decarbonization is clear, current policy measures are pulling in the opposite direction. The growing disconnect between Pakistan’s energy reforms and its climate obligations must be urgently addressed to preserve the country’s industrial future.

The objective of the IMF-backed policy – aimed at maximizing grid usage to lower tariffs by increasing consumption and spreading fixed costs over a broader base – has failed to materialize. Instead, frequent outages and rising costs have pushed consumers toward solar and industries toward alternative fuels like RFO, coal, and biomass.

What persists is an unreliable and unsustainable national grid, burdened with massive stranded costs. If these issues are not urgently resolved, they could lead to a permanent loss of industrial competitiveness and severe environmental consequences.

Meanwhile, the combined circular debt of the gas and power sectors has already exceeded Rs 5 trillion (as of March 2025) – a figure that will only increase if reliance on the fragile grid continues, expensive RLNG is diverted to the household sector, and domestic oil and gas fields are shut down.

Too often, policies are crafted in isolation, overlooking their long-term consequences on industrial vitality and export growth. Yet, in a landscape where fiscal reforms are essential, sacrificing sustainable revenue streams like exports is a risk Pakistan can no longer afford.

Therefore, an open cost-benefit analysis is urgently needed for all policies that currently overlook social, environmental, and economic costs to end this policy disconnect before the consequences become irreversible.


image_1753093309842.webp

April 23, 2025

By Shahid Sattar | Sarah Javaid
In the aftermath of World War II, a new world order emerged through the formation of institutions like the UN, IMF, World Bank, and WTO – established to promote stability and cooperation, allowing major powers to coexist within a rules-based global system.

But in 2025, that post-war order is visibly fraying. The WTO’s dispute resolution arm is barely functioning just as new tariff wars reshape the global order.

It is in this context that American billionaire investor Raymond Dalio offers insights through his thesis on the rise and fall of empires – The Big Cycle. He argues that new world orders often emerge from the ashes of disorder, and that it is strong leadership and strategic foresight that determine whether a nation rises or sinks during these transitions.

In every war, there are winners and losers – but Dalio notes that neutral nations in great-power conflicts often outperform even the victors. During WWII, nations like Switzerland, Turkey, and Sweden avoided destruction and leveraged neutrality to grow economically and politically. They maintained trade with both sides, served as financial hubs, and positioned themselves for post-war growth.

While the U.S. and China escalate their rivalry today, nations in the middle may quietly grow stronger, richer, and more stable. India is a visible candidate – leveraging the tariff war to expand its influence, attract investment, and secure strategic deals, all without being a frontline player in the conflict.

But can Pakistan do the same?

To navigate the evolving world order as a beneficiary rather than a bystander, Pakistan must balance its foreign relations while undertaking institutional reforms at home. For this shift to occur, it first needs to avoid internal dysfunction (such as weak governance) and external collapse (like mounting debt and fiscal mismanagement).

The Big Cycle explained:

Dalio’s thesis can be summarized simply: economies rise, peak, and then decline. But first, they must rise.

As economies ascend, they are marked by strong institutions, capable leadership, technological progress, innovation, education, efficient resource allocation, and growing competitiveness. A wealth-generating class emerges, creating prosperity for both itself and the nation – enabling the country to capture a larger share of world trade as financial institutions such as banks and markets begin to thrive.

At their peak, however, economies face rising debt, internal discord, and dwindling reserves – signs of decline before emergence of a new order.

The Rise and Fall of Nations:

Today, India represents a country in the ‘rising phase’ of Dalio’s Big Cycle: strong GDP growth (6.5%), robust foreign reserves ($676bn), booming merchandise exports ($437 bn) and expanding geopolitical relevance. Vietnam, too, is capitalizing on the China+1 strategy, with export growth, FDI inflows, and a competitive manufacturing base.

Eventually, nations reach a ‘tipping point’ where sustained prosperity leads to complacency, rising debt, and reduced competitiveness. A relevant example is the US, which, despite being the world’s leading power, shows signs of institutional dysfunction, political polarization, and declining competitiveness, with average annual GDP projected to fall to 1.9% in 2025 from 2.5% last year. Similarly, China, after decades of rapid expansion, now grapples with structural challenges – tariffs, market crisis, demographic decline, and excessive state control.

Finally, a country enters the ‘declining phase,’ where strengths like innovation, productivity, and leadership erode, and structural weaknesses – high debt, unrest, and capital flight – begin to dominate. Libya, once Africa’s wealthiest nation with over $100 billion in reserves, collapsed due to its authoritarian and archaic regime, civil unrest, and weakened institutions. Similarly, Sri Lanka faced a severe economic and political crisis after years of mounting debt, fiscal mismanagement, and fragile institutions.

Pakistan’s Halfway to Prosperity:

Unlike classical cases, Pakistan’s Big Cycle was truncated, with early gains stunted before reaching their full peak. Post-independence, Pakistan showed signs of growth with industrialization, strong GDP growth, infrastructure development, and export-led growth in textiles and rice. International institutions saw potential in its economy, but this rise was short-lived, largely confined to select regions, deepening political and regional inequalities.

The decline began prematurely amid political disorder, tensions with India, and the 1971 partition. Nationalization reversed gains, and reliance on aid replaced reforms. Successive regimes prioritized short-term stability over institution-building. The lack of adherence to any constitutional arrangement further accelerated the economic decay.

Since then, Pakistan’s early growth plateaued, constrained by poor governance, regional conflict, and external dependence – manifesting in persistent twin deficits, escalating public debt, loss-making SOEs, institutional decay and stagnant productivity.

What does this decline look like today? 2025 numbers provide a glimpse.

Pakistan on the Wrong Side of the Economic Curve:

The total debt and liabilities now stand at 83% of GDP, placing Pakistan 27th globally. Such levels are typically seen in either dynamic economies (US, UK) or collapsed ones (Sri Lanka, Sudan). To maintain its debt stability, Pakistan needs GDP growth exceeding the interest rate on its debt. However, projections suggest growth will barely reach 2% by FY25.

The SBP’s net reserves of $11.25 billion remain insufficient to cover even two months of imports, as imports are projected to reach $57.7 billion in FY25, or 15.5% of GDP. With unsustainable reserves, Pakistan has become the largest IMF beneficiary, having entered into 25 loan arrangements. Weak financial inflows strain the already fragile revenue system, further pressuring external accounts. The current account balance relies heavily on remittances – an unsustainable crutch. Though celebrated annually, remittances reflect the export of talent and intellect. There is ample evidence showing that an increase in remittances does not necessarily drive economic growth (more on this in an upcoming article). Meanwhile, exports, the basis for sustainable growth, now account for just 8.4% of GDP in 2024, down from 10.5% in 2000.

As a result, incentives for creating sustainable wealth are diminishing. Irrational tax policies, such as EFS, unjustified tax rates, and a narrow tax base, have eroded business confidence. Tax collection, revised downward by the IMF, continues to lag, eventually shifting the burden to already-taxed segments. Inflation has eased, primarily due to base effects and falling food prices, rather than an improvement in purchasing power. Household expenditures now consume 89% of the average monthly household income. Eroding purchasing power and difficult business conditions have slowed demand and business activity, contributing to economic stagnation, as reflected in negative industrial output in 8 of the last 10 quarters.

This is the decline Pakistan is facing. According to Dalio, debt doesn’t just grow – it compounds, triggering ripple effects across communities. Consumption falls, inflation rises, trust in institutions wanes, and confidence in the currency erodes. Investors pull back, and citizens lose faith in the system.

Acemoglu and Robinson sum it up in Why Nations Fail: “Nations fail because their extractive economic institutions do not create the incentives needed for people to save, invest, and innovate.” (A must-read for serious students of Pakistan’s economics.)

A Dalio-Inspired Path to Growth:

In today’s shifting global order, increasingly shaped by the U.S., Pakistan has the opportunity to emerge as a strategic gainer – if it remains neutral and focuses on the strategic steps outlined by Dalio: strong governance, innovation, education, efficient resource allocation, competitiveness, and robust markets.

To begin with, Pakistan must focus on the basics: fiscal consolidation. Despite high tax rates on individuals and businesses, the country has one of the lowest tax-to-GDP ratios. The focus must shift from high rates to a broader base and from indirect to direct taxes. In 2024, the FBR collected 51.2% of revenue from indirect taxes (ST, FED, CD) compared to 48.4% from direct taxes. With the informal economy estimated at 30–35% of GDP, formalization and better compliance are essential to increase direct tax collection. A World Bank study reveals that untaxed sectors, like agriculture, contribute only 10% of their tax revenue potential. Bringing these sectors into the net is crucial for fiscal discipline.

Another fiscal pressure point is the financial burden of SOEs. As of FY24, their aggregate losses amounted to 6% of GDP (Rs.5.7 trillion), which is higher than the FBR’s direct tax revenue (Rs.4.5 trillion). Despite privatization being on the agenda since 1991, the government continues to provide budgetary support (Rs196 billion in FY25) to keep them running. Reforming or divesting loss-making SOEs is crucial to ease fiscal burden.

Dalio also stresses diversification of investment to hedge risk. For Pakistan, this means shifting from speculative real estate to export-oriented sectors – an outcome that hinges on restoring business confidence. High taxes, rising input costs, and low confidence push capital into unproductive sectors. Ahmed Jamal Pirzada recently noted that registered companies in Pakistan are increasingly investing in real estate. A stable business climate is the first step toward reversing this trend.

Dalio’s thesis further underscores that major economic powers rise through productivity and innovation. Pakistan must boost both. From 2000 to 2020, its labor productivity grew just 1.5%, far behind India (5.7%), Bangladesh (3.9%), and China (8.5%). With only 0.55% of budget allocated for education versus 7.42% on PSDP, rebalancing is vital. Investing in skills education can enhance productivity, improve job outcomes, and reduce brain drain.

Geopolitically, Pakistan must pursue a balanced approach. While it maintains strategic ties with both China and the U.S., retaliatory tariffs could damage relations with the U.S., while offering preferential tariffs to the U.S. might strain ties with China. Therefore, it is essential to uphold strategic neutrality, safeguard sovereignty, and pursue targeted reforms for post-war recovery.

Dalio’s roadmap – centered on debt control, fiscal discipline, and neutrality – offers Pakistan a path to resilience. However, to achieve this, the country must first reboot its economic mindset and policymaking framework. By adopting institutional reforms and positioning itself as a neutral gainer in the emerging global order, Pakistan has the potential to transform today’s crisis into a long-term advantage – much like the neutral nations of the post-WWII era.


image_1752127494833.webp

April 16, 2025

While the current decline in global energy prices would benefit most manufacturing economies, it poses a serious challenge for Pakistan’s export industry.

Over the past few weeks, Brent crude has dropped from ~$75 to ~$65 per barrel, expected to decline even further. As global energy prices fall, regional competitors are gaining access to gas at much lower rates—between $5–7/MMBtu. In contrast, gas for captive power generation in Pakistan is Rs. 4,291/MMBtu ($15.38), including the misplaced levy of Rs. 791/MMBtu. This puts Pakistan’s exporters at a severe disadvantage.

Countries like Bangladesh, where—per an ADB survey—80% of the industry runs on gas-based captive power, will benefit greatly from cheaper gas prices. Similarly, industries in India, China, Bangladesh and Vietnam are paying just 5–9 cents/kWh for electricity, while Pakistani industrial consumers face 11–13 cents/kWh from the grid.

For an energy-intensive and low-margin sector like textiles, this energy cost differential makes it extremely difficult to compete internationally.

China’s recent imposition of a 34% tariff on US LNG, effectively pricing American cargoes out of the Chinese market—will significantly alter global LNG trade flows. With landed costs rising to $9.75–$12.50 per MMBtu—compared to Qatar’s $7–$9 and even cheaper Russian pipeline gas—US LNG becomes commercially unviable for Chinese buyers. As a result, cargoes are being rerouted to Europe, where the sudden supply influx has already triggered a 7.5% drop in TTF prices.

This shift tightens the US–EU LNG arbitrage window, strains regasification infrastructure, and underscores how geopolitical tariffs can rapidly reshape market dynamics. The move also reinforces China’s long-term strategy to diversify supply through stable, lower-cost alternatives like Qatar and Russia, while minimizing exposure to volatile spot markets.

A sustained decline in Brent crude prices towards $50 per barrel could create significant headwinds for the U.S. liquefied natural gas (LNG) industry, which operates on a pricing structure based on Henry Hub gas prices plus liquefaction and shipping costs. This model becomes less competitive when oil-indexed LNG—especially from low-cost producers like Qatar—becomes more attractive in a low-Brent environment.

The global LNG market is poised for significant structural change by 2030, with approximately 170 MTPA of new liquefaction capacity expected to come online, led by the U.S. and Qatar, with additional volumes from Russia and Canada. Concurrently, over 65 MTPA of long-term contracts are set to expire, and 200–250 MTPA of LNG—more than half of today’s global trade—will need to be re-marketed or re-contracted by 2030.

Given these factors, LNG prices are expected to further decline in coming months and sustain at low levels.

Meanwhile, Pakistan’s LNG market is dominated by state-owned enterprises which hold long-term Sale and Purchase Agreements (SPAs) under take-or-pay terms. These entities also control import terminals and pipeline infrastructure, creating high entry barriers for private sector participation.

Pakistan currently imports 7.5 million tonnes per annum (MTPA), or approximately 1,000 MMCFD, through long-term LNG contracts. SNGPL is the primary off-taker for PSO’s contracts, while K-Electric has taken over PLL’s ENI contract. The main contracts are:

Table 1. Pakistan Long-Term RLNG Contracts

Contract % of Brent End Date Million mt/year
PSO-QG 13.37 Jan-31 3.75
PSO-QP 10.2 Dec-32 3
PLL-ENI 12.14 Nov-23 0.75

The RLNG sector faces persistent challenges due to poor demand forecasting, lack of downstream take-or-pay commitments, and an absence of a competitive gas market. These structural gaps have led to growing mismatches between supply and demand. Currently, SNGPL is dealing with surplus RLNG volumes equivalent to 18 unutilized LNG cargoes annually—projected to exceed 40 cargoes as gas demand for captive power generation, the largest off-taker of RLNG after the power sector, is being destroyed through prohibitive pricing to increase utilization of the national grid.

LNG was envisaged to replace high-speed diesel (HSD) and furnace oil (FO) in power generation (FGE 2015), with government-owned RLNG power plants as the primary off-takers. Over time, however, the power sector has significantly reduced its reliance on RLNG, opting instead for cheaper alternatives such as coal, nuclear, hydro, and solar. Moreover, RLNG demand is inherently volatile—affected by seasonal variations, transmission constraints, plant availability, and shifting merit order priorities.

The four major RLNG-based power plants—Bhikki, Balloki, Haveli Bahadur Shah, and Trimmu—initially operated under 66% take-or-pay clauses in their Power Purchase Agreements (PPA) and Gas Sale Agreements (GSA). These terms guaranteed a minimum payment to SNGPL, ensuring revenue even if full gas volumes were not used. In 2021, the Economic Coordination Committee (ECC) waived the 66% requirement, allowing monthly dispatch flexibility (0–100% capacity) based on demand. This was partially reinstated in 2023, with a minimum 33% take-or-pay threshold introduced for financial assurance. However, these revisions were never formally integrated into the contracts, leading to ongoing billing disputes between plant operators and SNGPL.

These RLNG power plants remain underutilized due to high generation costs—around Rs. 26 per kWh—with current offtake down to 286 MMCFD, well below contracted volumes. As a result, SNGPL is left managing stranded RLNG volumes, while incurring rising financial liabilities. To absorb surplus gas, RLNG is diverted to low-revenue domestic consumers at a subsidy of approximately $12.19/MMBtu. This is a key driver of the gas sector’s circular debt, which now exceeds Rs. 2.7 trillion (IMF, 2024).

Compounding the issue is the ongoing decline in indigenous gas production, with major fields like Sui and Qadirpur reduced by a combined 200 MMCFD. To accommodate surplus RLNG under take-or-pay constraints, indigenous gas production is being curtailed—disrupting merit order dispatch and increasing electricity costs via fuel cost adjustments (FCA). The structural oversupply of RLNG is projected to persist well beyond 2024.

In this context, phasing out captive power plant consumption through prohibitive pricing, including the ill-conceived and mis-calculated grid transition levy, will exacerbate the imbalance. Captive users currently account for roughly 20% of RLNG offtake within the Sui network. Removing this demand will intensify surplus volumes, trigger take-or-pay penalties, increase unaccounted-for gas (UFG), and create operational bottlenecks. These penalties are passed on to end-consumers under existing policies, further inflating gas tariffs and undermining affordability.

The financial burden is not limited to SNGPL. As surplus grows, storage constraints and high pipeline pressure (line-pack) create a risk of forced indigenous gas curtailment. This threatens the financial viability of local Exploration and Production (E&P) companies and risks stranding recoverable reserves.

If elimination of gas-fired captive power generation proceeds as planned, the RLNG surplus could exceed 40 LNG cargoes annually—creating a structural oversupply that jeopardizes the entire gas value chain (Figure 1). In such a scenario, the financial sustainability of state-owned entities in the petroleum division may come under serious threat.

Figure 1. Projected RLNG Surplus in SNGPL Network from Crowding Out of Captive

This is already reflected in the Sui companies’ demand to raise consumer gas prices. In their revenue requirements for FY26, SNGPL has proposed increasing the prescribed price of natural gas from approximately Rs. 1,750/MMBtu to Rs. 2,485/MMBtu, citing the RLNG diversion cost of over Rs. 300 billion as a key driver. Similarly, SSGC has requested a steep hike to Rs. 4,137/MMBtu.

These losses are occurring while domestic gas demand is being deliberately curtailed—particularly from industrial and captive power consumers—creating further inefficiencies. At the same time, policy decisions have also curtailed 200-400 MMCFD of low-cost indigenous gas priced at less than $4/MMBtu, undermining local exploration and production (E&P) activity and deepening reliance on expensive imported LNG.

The ridiculousness of the situation can be gauged by that we are importing LNG at $10-12/MMBtu, while curtailing domestic production that costs less than $4/MMBtu in an extremely tight balance of payments situation.

In the years ahead, the global LNG market is expected to loosen due to upcoming liquefaction capacity expansions in the U.S. and Qatar. By then, Pakistan will be obligated to take delivery of previously deferred long-term cargoes—likely at prices well above prevailing market rates. Currently, the government is selling those same cargoes below market value, locking in a loss both now and in the future. This approach reflects poor sequencing and undermines energy affordability and fiscal stability.

Pakistan’s long-term LNG contracts offer pricing stability and volume security, protecting buyers and sellers from market volatility. However, clauses like “Net Proceeds” in Qatar Gas (QG) and Qatar Petroleum (QP) contracts allow the seller to resell cargoes and retain any excess earnings if the buyer does not take delivery. While contractually permissible, this mechanism heavily favours the seller in oversupply scenarios. There is a strong case for Pakistan State Oil (PSO) to review and renegotiate such clauses in future SPAs to ensure a more equitable allocation of gains and risks.

Figure 2. Pakistan LNG Contracts vs. International Spot Market

Moreover, this has enabled foreign companies to capture arbitrage profits of over $300 million—approximately $100 million from 5 Qatar cargoes and $200+ million from 11 ENI cargoes. This was driven by high TTF prices in a tight global spot market, as Europe competes with Asia this year (Figure 2). For instance, selling cheap ENI cargoes in a tight global LNG market results in about $19 million arbitrage, TTF went $17+ per MMBtu in February 2025.

It is concerning that Pakistan deferred 5 cargoes in a tight global LNG market when next year’s spot LNG prices are expected to be cheaper than long-term contracts, as the US and Qatari liquefaction waves hit the market. This year’s term contracts were already much cheaper, before the brewing U.S.-China trade was further weighed down on energy markets.

At a Brent crude price of $60 per barrel, LNG import prices under existing SPAs are approximately $6.12/MMBtu (Qatar Petroleum, 10.2% slope), $8.02/MMBtu (Qatar Gas, 13.37% slope), and $7.28/MMBtu (ENI, 12.14% slope).

At a time when global Brent and LNG prices are in decline—and Pakistan remains locked into long-term LNG contracts—the government is compounding policy errors by pricing gas-fired captive power generation out of the market and undermining industrial competitiveness.

It is one of many self-inflicted wounds. Instead of leveraging long-term LNG contracts Pakistan is wasting them. At $60 Brent, delivered LNG under current SPAs is priced between $6 and $8/MMBtu. These volumes should be directed to industries to enable self-generation of competitive power, not offloaded at a loss or used to subsidize low-efficiency consumption. The decision to penalize industrial captive use during a window of favourable global pricing reflects a serious misalignment between procurement strategy and downstream policy.

The government must urgently revisit its gas pricing framework. RLNG should be supplied to industrial captive cogeneration consumers at its full actual cost—excluding the burden of cross-subsidies to other sectors, extraneous surcharges like the grid transition levy, and inflated UFG assumptions. Doing so would restore a rational basis for industrial input pricing, improve power system efficiency, and reduce fiscal stress on the gas chain.

Longer term, Pakistan must accelerate liberalization of the LNG and downstream gas markets. This includes immediate implementation of transparent Third Party Access (TPA) protocols that allow private buyers and sellers to engage in B2B arrangements and utilize pipeline capacity and regasification terminals on a non-discriminatory basis. Continued reliance on opaque G2G deals through Pakistan LNG Limited (PLL)—such as recent engagements with SOCAR—only entrenches inefficiencies and exposes the system to non-market risks, including rent-seeking behaviour.

A liberalized market structure, grounded in competitive procurement and infrastructure access, will drive investment, improve price discovery, and provide a foundation for supply security through diversified sourcing.


image_1753093434290.webp

April 14, 2025

By Shahid Sattar | Sarah Javaid
Pakistan’s export sector is undergoing a seismic shift, one that will affect its competitive edge for years to come. The U.S. has imposed ‘reciprocal tariffs’ globally, including a 29% duty on Pakistan, as part of its protectionist policy.

The misaligned trade diplomacy – relying on the U.S. as its largest market for value-added exports while maintaining an intertwined supply chain with China – underscores how the 29% tariff is merely the first step toward a deeper economic pit that Pakistan risks falling into.

Structural inefficiencies – worsened by regressive taxation and ill-conceived energy policies – have already eroded Pakistan’s export competitiveness. This year marked a turning point when over 50% of Pakistan’s textile import bill was dominated by cotton and cotton yarn – a trend never seen before. Once a leading producer, Pakistan is now increasingly reliant on imports, with cotton yarn imports expected to surge nearly 200% and the cotton import bill projected to rise by over 50% this financial year. Together, these are projected to cost the economy a staggering $2.8 billion, with the combined total for cotton imports and textile intermediates reaching $4.4 billion.

While Pakistan sources the bulk of its raw cotton from the U.S. and Brazil, over 60% of its cotton yarn imports – cheaper than domestic yarn – now come from China, raising concerns over potential dumping and associated compliance risks.

As we officially enter the global trade war, beyond tariffs, another non-tariff threat looms: the potential for a U.S. ban on Pakistani exports.

In 2019, the U.S. banned Chinese cotton from Xinjiang over forced labor concerns, extending restrictions to any product containing Xinjiang cotton, regardless of origin.

However, through strategies such as China Plus One, transshipment, and third-country exports, China has sustained its presence and deepened its hold on the global textile supply chain. In 2024, China exported $3 billion worth of cotton intermediates to eight South Asian countries, including Pakistan, accounting for 30% of its $10.8 billion global exports in this segment.

While Pakistan didn’t directly benefit from China Plus One, it has become a key market for cheap Chinese textile intermediates, including knitted and woven fabrics, filament yarn, and cotton yarn.

Despite U.S. policies and growing supply chain scrutiny, Pakistan remains one of the largest importers of Chinese cotton yarn. And this is where the fire begins.

Pakistan’s Trade Dilemma – Cheaper Imports from China and Compliance Risks:

With a sharp decline in local cotton production, Pakistan has increasingly turned to cotton imports from the U.S. and Brazil, which now account for over 60% of total imports. In fact, Pakistan is the second-largest importer of U.S. cotton.

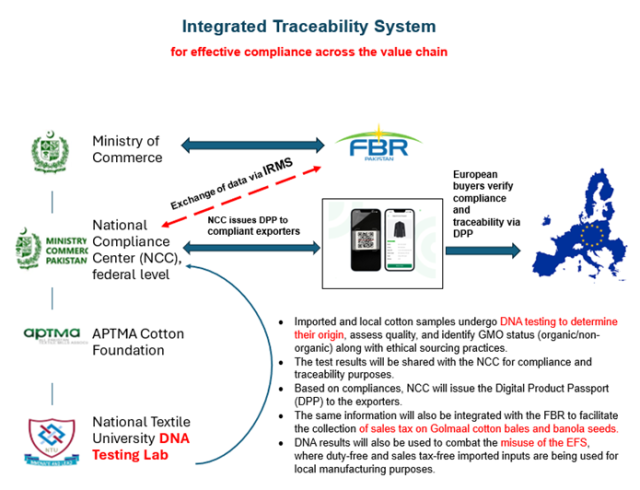
Simultaneously, the country has become the top importer of cotton yarn from China. This shift has strained the local spinning industry and at the same time introduced compliance risks, particularly due to the potential inclusion of Xinjiang cotton in Pakistan’s textile supply chain, especially in the absence of a traceability mechanism.

Since Xinjiang produces 87% of China’s cotton, China has redirected its (non-tradable) cotton toward textile manufacturing in response to U.S. bans. Additionally, it has implemented a tariff-rate quota system on cotton imports, ensuring that textile manufacturers primarily rely on Xinjiang cotton.

As the U.S. strengthens oversight of textile supply chains, any trace of Chinese cotton in Pakistani textile exports could result in bans in the US market for apparel.

The key question remains: What is driving Pakistan’s growing reliance on imported cotton yarn?

Price Disparities and the Absence of a Competitive Edge for Local Yarn:

The Chinese textile and apparel industry benefits from extensive subsidies. Under the Make in China initiative, the government has introduced over 900 subsidies to support local manufacturing.

In contrast, Pakistan’s textile sector faces mounting challenges, particularly following the reversal of regionally competitive tariffs and the withdrawal of zero-rating on local supplies under the EFS scheme. Power tariffs have hit record highs of 12–14 cents per kWh (the highest in the region), and the price of gas for captive power plants has surged to Rs. 3,500/MMBtu, with an additional levy of Rs. 791/MMBtu. Beyond energy costs, the rising prices of other textile inputs have further undermined the competitiveness of yarn production in Pakistan, making it increasingly difficult to compete with cheaper, duty-free Chinese imports.

China’s pricing advantage in textile intermediates is evident in its export rates. For most traded cotton yarn tariff lines, the prices offered to Pakistan are not only lower than those offered to Vietnam and Bangladesh (Table 2a), but also well below Pakistan’s domestic yarn prices (Table 2b). This cost edge enables China to maintain its competitiveness in the Pakistani market, while leaving Pakistani yarn manufacturers struggling to compete in a market distorted by cost disadvantages.

China’s Strategic Emphasis on Maintaining Low Production Costs:

The cost and pricing edge is no accident. China controls over 50% of global spinning capacity and 45% of fabric manufacturing, and in response to increasing global trade restrictions, it is doubling down on its domestic textile sector. Plans are underway to expand spinning capacity in Xinjiang and raise the cotton-to-textile conversion rate from 40% in 2024 to 45% by 2028. Generous subsidies for transporting cotton from Xinjiang to central and eastern provinces further reduce production costs and incentivize yarn manufacturers.

With this level of government support and massive economies of scale, China is able to export yarn and other intermediates at competitive prices – often lower than the prevailing prices in importing countries.

Here the challenge for Pakistan is threefold: protecting its local industry from potential dumping, managing compliance risks tied to increased dependence on Chinese imports, and securing preferential access to key export markets, particularly the U.S. and EU, where Pakistan’s value-added textiles are primarily destined.

The Current State of Cotton Yarn Imports in Pakistan:

China’s competitive edge in yarn is also visible in Pakistan’s import patterns. The most traded cotton yarn import tariff lines in Pakistan account for 100% of imports from China, which were initially subject to an 11% MFN duty (Table 3a). However, under the 5th Schedule of Pakistan Customs, these duties were reduced to 5%, and the China-Pakistan Free Trade Agreement further lowered them to 4.2%.

Moreover, exporters can access duty-free yarn imports under the EFS scheme. The combination of low export prices and 0% duty has made Chinese yarn highly competitive in the domestic market – crowding out local production.

In contrast, peer economies such as India and Bangladesh have adopted a more defensive policy posture, protecting their local industries through higher duties on Chinese yarn as reflected in their respective customs schedules (Table 3b).

A Global Snapshot:

Under WTO rules, countries can impose anti-subsidy or countervailing duties to protect domestic industries from unfair price advantages created by subsidies from trading partners.

Recently, several countries have initiated anti-dumping investigations and imposed duties in response to unfair trade practices by China.

For example, the European Commission recently imposed anti-dumping duties (26.3% to 56.1%) on Chinese glass fiber yarn imports to protect 1,200 EU jobs and restore market competition. The investigation found that Chinese imports were harming local industry.

In December 2024, India launched investigations into the alleged dumping of nylon filament yarn and trimethyl dihydroquinoline (TDQ) from China, with potential recommendations for duties.

In September 2024, Turkey initiated an anti-circumvention investigation into synthetic staple fiber woven fabrics from Malaysia, suspecting that these imports were bypassing existing anti-dumping measures on China, as the share of Malaysian imports rose sharply in 2023 and 2024.

In June 2025, Malaysia announced provisional anti-dumping duties (6.33% to 37.44%) on polyethylene terephthalate (PET) imports from China and Indonesia.

Egypt also extended anti-dumping duties on Chinese synthetic fiber blankets, maintaining tariffs of 55% to 74% until August 2025 to prevent a surge of dumped products in its market.

Urgent Call for Government Intervention to Ensure Fair Trade:

Given the global trend of rising anti-dumping measures, Pakistan faces a similar threat to its domestic industry. With heightened trade restrictions on China from the U.S., such as increased tariffs and escalating non-tariff barriers, there is a growing risk of more dumping of cheaper textile intermediates, and local manufacturers risk being priced out of their own market.

The National Tariff Commission (NTC) has previously acted decisively – even imposing anti-dumping duties on relatively low-impact products like lead pencils from China. Today, the stakes are much higher, involving Pakistan’s largest export sector, millions of livelihoods, and billions in export revenue. With the margin for error narrowing, Pakistan must take urgent and well-calibrated action to safeguard its textile industry from unfair competition.


image_1751957313260.webp

March 31, 2025

Pakistan has reached a staff-level agreement with the IMF, meaning the economy gets to stay afloat for another six months.

However, behind the superficial macroeconomic stability is only economic stagnation with no real reforms in sight as the government continues to cling to the same distorted policy choices that that have propped up a broken system for many decades. The slogans have certainly become more progressive, but the intent remains to preserve the status quo at all costs, no matter how damaging it is to the productive sectors and people that actually comprise the economy.

There’s no better example of this than energy policy.

Over the last several months, closed-door promises and public statements have been made at the highest levels that electricity for industry will be brought down to 9 cents/kWh by April 2025. However, April is here, and that ship seems to be sailing in a different direction.

Industrial power tariffs have indeed come down from over 17 cents/kWh in January 2024 to about 12 cents/kWh at present, largely due to negative fuel cost and quarterly adjustments. However, things are in the danger zone again as February 2025 saw a sizable drop in power consumption, below the reference level. This triggers upward pressure on the QTA, and depending on the March numbers, we could be looking at increasing tariffs again.

There was also hope within some circles that raising gas prices to punitive levels would shift enough captive load to the grid for a sizable reduction through the QTA mechanism. Gas price for captive was increased to Rs. 3,500/MMBtu, with an additional “grid transition levy” of Rs. 791/MMBtu to increase the cost of gas-fired captive beyond grid electricity tariffs.

The levy itself is fundamentally flawed and deliberately miscalculated, given that at Rs. 3,500/MMBtu, captive generation costs 14-18 cents/kWh—more expensive than grid electricity of ~12 cents/kWh. The calculation includes glaring errors, including the use of the B-3 peak rate, applicable for only 4 out of 24 hours, instead of a weighted average of peak and off-peak rates. This, along with other factual inaccuracies, are designed to artificially inflate the levy and force a shift to the grid.

However, industries face significant challenges in shifting to the grid. Pakistan’s grid price remains significantly higher than regional benchmarks, which range between 5–9 cents/kWh, and the industry can not compete internationally with such input cost differentials, especially in something as major as energy. Moreover, in urban hubs like Karachi, there is not enough physical space for installation of infrastructure to connect captive users with no power connections to the grid. In other areas, such as those served by HESCO, the grid infrastructure is outdated and incapable of supporting large additional industrial loads.

Furthermore, cogeneration captive plants—which utilize the same gas molecules to produce both power and process heat for applications like steam and hot water—offer far superior efficiency and productivity than the grid.

Yet, the government wants industry to abandon these plants, many of which were installed following the Cabinet Committee on Energy (CCOE) 2021 decision to phase out single-cycle captive while allowing cogeneration to continue. Investment of Rs. 128 billion for upgradation and cogeneration will become sunk, while industries will be forced to make new investments in gas-fired boilers and chillers with significantly lower efficiency.

It makes no economic sense to supply gas at Rs. 2,200/MMBtu for production of hot water and steam in low-efficiency systems while shutting down combined cycle heat and power plants that are willing to pay full RLNG price (Rs. 3,550/MMBtu) and operate at net power and thermal efficiencies of up to 90%.

Cogeneration is internationally recognized as the gold standard for industrial energy efficiency. It is actively promoted in developed economies such as the United States and the European Union, as well as emerging economies like Indonesia. Additionally, cogeneration plays a crucial role in Pakistan’s compliance with global climate commitments, including the EU Carbon Border Adjustment Mechanism (CBAM) and broader net-zero targets. Unlike inefficient grid electricity, which relies on relatively high-emission thermal sources, gas-fired cogeneration enables industries to lower their carbon footprint while ensuring cost-effective energy production. However, while industries worldwide are harnessing cogeneration benefits, Pakistan is actively eliminating it.

The entire captive power fiasco is characteristic of the of the broader governance and transparency failures that plague the energy sector and the economy. There is constant rhetoric about policy consistency and reform, yet in practice, there is utter disregard for due process, principles of efficiency and economic allocation, or even basic facts like what is the B-3 industrial power tariff.

The 2021 CCOE decision, which explicitly permits cogeneration, is repeatedly misrepresented to justify a blanket elimination of all captive power. No one appears willing to read the policy they cite:

“If a Captive Power Plant claims to be a co-generation unit, it shall make such a declaration latest by 01.02.2021. NEECA will conduct a third-party audit of all such Captive Power Units (Export/Non-Export) claiming to have a co-generation facility within 3 months in order to avoid rent-seeking capacity against continued gas supply to such units. If the audit confirms the cogeneration facility, gas supply will continue but otherwise it will be disconnected. Power Division shall finalize the detailed and transparent mechanism for third-party audit within one week.”

A common counterargument is that the industry itself blocked progress by obtaining a stay on the audits. This narrative is misleading and selective. First, the stay was secured by certain players through legitimate legal channels available under the law—it was not a case of non-compliance or refusal to undergo audits. Second, and more importantly, there is a substantial segment of the industry that invested billions to upgrade to cogeneration facilities in line with government policy. Many of these companies have formally and repeatedly requested audits from NEECA to verify their compliance and efficiency, yet no audits were conducted.

This misrepresentation runs parallel to the deliberately and very clearly flawed calculation of the “grid transition levy,” constructed on manipulated assumptions for the sole purpose of justifying a pre-decided policy.

The whole episode reflects a system where rules are bent, facts are ignored, and policy is reduced to an exercise in reverse engineering—starting with the outcome and fabricating the justification to match. It also sends a powerful message to the outside world: policy in Pakistan is fluid, unpredictable and detached from any logic, reality or legality. With this kind of governance on display, it’s no mystery why any serious investment continues to bypass the country.

In any case, only a fraction of the captive load is actually shifting to the grid. Most manufacturers are choosing other options—fuel oil or coal-fired plants integrated with solar setups that are cheaper and more reliable. And the government is trying to kill that too.

So, industry is being choked off from every angle. Grid prices are too high, and infrastructure is inadequate. Captive is being over-regulated and misrepresented. The renewable route is also being discouraged. There is no viable way forward being offered—only a series of dead ends.

Meanwhile, while industry is suffocating, housing societies are paving the way for their own distribution companies with private supply. For years, industry has asked for B2B power contracts with rational and internationally standard wheeling charge of 1-1.5 cents/kWh. But CPPA-G has gone out of its way to sabotage these efforts by being adamant on a Rs. 27/kWh (~9.7 cents) wheeling charge, which includes stranded costs and cross-subsidies of the grid and is more than the full cost of electricity in most countries. The message is loud and clear: protect the inefficient, failing grid at the cost of every other priority.

Gas sector “liberalization” is following the same pattern of blatant rent-seeking. The Council of Common Interests (CCI) approved third-party access to 35% of new domestic gas discoveries. But those fields are quietly handed out without competitive bidding while multiple interested players offering better terms are sidelined in favour of politically connected entities.

Simultaneously, the decline in captive demand has created a significant surplus of RLNG in the system. Rather than addressing the core issue, the response has been to curtail cheaper domestic gas production to absorb the RLNG and avoid pipeline overpressure. As a result, RLNG is now being supplied to domestic consumers at heavily subsidized rates—subsidies that are being financed through an ever-deepening gas sector circular debt. Meanwhile, portions of the Qatari RLNG cargoes are being offloaded to Europe and other markets at steep discounts, incurring substantial costs to the government. All this while domestic industry—willing to pay full price for the same RLNG—is denied access. The absurdity is hard to overstate.

We’re at the point where grid tariff reductions are no longer possible without major reform of the power sector and tariff structure, like removing the Rs. 100 bn cross subsidy from industrial power tariffs. There are rumours that the government is planning another incremental consumption scheme. After a disastrous winter package, one would hope lessons have been learnt. Any such scheme must be based strictly on marginal cost pricing, use last year’s consumption as a simple and straightforward benchmark with a generous cap on savings. Otherwise, it is bound to fail.

More broadly, a much more radical reform of the energy regime is needed to fix the deep-rooted rot that continues to erode competitiveness and confidence across the economy. Officials across government ranks and department know this and acknowledge it. Yet, nothing gets done. Every proposal dies in a sub-committee or is buried under a stack of “deliberations.” Decision-makers are more interested in conducting photo-ops and signing MoUs.

The rest of the world is moving forward. Distributed generation. Renewable integration. Flexible power models tailored to industry needs. Meanwhile, Pakistan’s policymakers are clinging to a grid that is inefficient and financially unsustainable. And it’s at a point where they’re doing so by destroying the few parts of the system that do work.

Captive users should be allowed to procure gas at ring-fenced RLNG rates, free from cross subsidies, inflated network losses and arbitrary surcharges. At full RLNG pricing, generation from single-cycle captive plants is already more expensive than the grid, and the market will naturally phase them out. Only efficient cogeneration systems—justified on both economic and technical grounds—will remain, as they should.

In parallel, industry must be granted access to 35% of new domestic gas under the Third Party Access framework. Allocation should be determined through transparent, competitive bidding based on market value, not political influence. Likewise, direct LNG imports must be allowed without obstruction. All the necessary legal frameworks, terminal infrastructure, and pipeline capacity already exist—the only obstacle is bureaucratic resistance and policy inertia. These are straightforward, market-driven policies. They require no subsidies, no special treatment—just the removal of distortions.

Real economic growth will only be possible under a supportive energy regime. The existing approach is fundamentally misaligned with Pakistan’s broader industrial and export goals. It is imperative that the government reassess its direction and ensure that energy allocation and pricing are rooted in principles of efficiency, competitiveness, and fairness.


image_1753072508936-1280x717.webp

March 14, 2025

By Shahid Sattar | Sarah Javaid
Pakistan’s trade deficit has widened by 16% to USD 14.1 billion in the first seven months of FY 2025, compared to USD 12.2 billion during the same period last year (SPLY). On average, the monthly deficit has been increasing by 3%, currently averaging USD 2 billion per month. If this trend continues, the deficit could reach USD 26 billion by the end of the current fiscal year – or even higher at USD 27.8 billion.

While global trade, including Pakistan’s, faces uncertainty amid U.S.-triggered tariff wars, Pakistan’s policy missteps have worsened the situation, leading to a significant shift in its trade dynamics.

A key concern is the growing reliance on textile imports – a sector that has always operated at a surplus.

This drastic shift is a direct consequence of regressive taxation policies and soaring energy tariffs, which have crippled domestic production and eroded competitiveness.

If left unaddressed, this trend could have severe long-term consequences for Pakistan’s balance of trade.

Exports vs. Imports: A Worrisome Shift

During the first seven months of FY 2025, total exports grew by 10% to USD 19.5 billion, while total imports increased by 7% to approximately USD 33.3 billion. The petroleum and coal sectors led export growth, surging 85%, driven due to the zero-base effect of petroleum crude exports, followed by an 11% increase in textiles.

While these numbers may appear positive on the surface, a deeper look reveals a worrisome trend.

An analysis of import patterns indicates that the textile imports surged by 54% – the highest among all import groups. This stark reversal from same period in previous years, when textile imports declined by 38% in FY 2024 and 9% in FY 2023, highlights Pakistan’s manufacturing decline and the urgent need for corrective policy action.

What caused this shift?

During this period, cotton and cotton yarn accounted for 64% of total textile imports, up from 45% in SPLY – the highest composition ever recorded.

The primary reason is policy changes in the last budget. The Finance Act 2024 removed the zero-rating/sales tax exemption on local supplies for export manufacturing under the Export Facilitation Scheme (EFS), while imports remain duty- and tax-free. As a result, domestically sourced raw materials and intermediate inputs are now subject to an 18% sales tax, making local yarn more expensive than imported substitutes.

The consequences of this policy shift have been severe.

Domestic industry in decline, imports on the rise:

Over 100 spinning mills (~40% of production capacity) have shut down, while others are operating at below 50% capacity and are on the verge of closure.

Consequently, cotton yarn imports surged 276% in the first seven months of FY 2025 compared to SPLY. With an average monthly growth of 10%, they are projected to reach USD 737.4 million by year-end.

Even more concerning is that the surge extends beyond cotton yarn, with raw cotton imports rising sharply due to declining domestic production. During this period, imports soared to USD 1.12 billion – a 91% increase from USD 589 million in SPLY. At the current average monthly growth rate of 8%, total cotton imports are projected to reach USD 2.1 billion by year-end.

Given these trends, the combined import bill for raw cotton and cotton yarn is estimated to reach USD 2.84 billion – an 80% increase from last year’s USD 1.57 billion – posing a significant threat to Pakistan’s trade balance and the long-term viability of its textile sector, especially as protectionist policies disrupt global markets.

Pakistan’s Trade Deficit and the U.S. Tariff War: A Brewing Crisis:

Pakistan’s exports to the U.S. are dominated by textiles and apparel. During the first seven months of FY 2025, exports to the U.S. totaled USD 3.6 billion, accounting for 19% of Pakistan’s total exports. Of this, 79% (USD 2.8 billion) consists of textile and apparel products.

Among these textile exports, 94% are value-added, including ready-made garments and home textiles, while only 6% are textile intermediates. Despite this, Pakistan lacks a preferential trade agreement with the U.S.

Fair trade is a two-way street, but Pakistan’s trade with the U.S. tells a different story.

The U.S. GSP program, which expired in 2020, covered only 1.5% of Pakistan’s value-added exports to the U.S. that year and has not been renewed. Meanwhile, Pakistan’s value-added textile exports face tariffs of up to 17% in the U.S. market, while its cotton imports from the U.S. remain duty-free, creating a one-sided trade relationship.

As the second-largest importer of U.S. raw cotton – just behind China – Pakistan sourced nearly 50% of its total cotton imports from the U.S. in FY 2024.

This calls for a proactive approach to securing fair trade terms and reciprocal market access with the U.S.

The Unfair Tariff Burden:

The U.S. policy of imposing blanket tariffs globally, including on Pakistan, is unjustified. With 19% of Pakistan’s total exports and 37% of its textile exports directed to the U.S., the existing 17% tariff – combined with a potential additional 20% – would significantly erode competitiveness. Pakistan primarily caters to low- to middle-income consumers in the U.S., making its exports highly price-sensitive. This is especially concerning given that Pakistan’s energy tariffs (12–14 cents/kWh) are much higher than those of competing economies (5–9 cents/kWh), placing textile manufacturers at a severe cost disadvantage.

Beyond textiles, overall trade relations will also be impacted. Pakistan has alternative sources for cotton imports, such as Brazil – its second-largest supplier – making it possible to diversify away from U.S. cotton if trade restrictions worsen.

Wider Economic Consequences:

An erosion of export competitiveness due to U.S. tariffs and high energy costs will expose Pakistan to economic challenges far beyond a widening trade deficit.

In the short term (FY 25-26), declining exports will pressure the rupee, causing depreciation. As the rupee depreciates, the cost of essential imports – especially those with inelastic demand like energy, food, and raw materials – will rise, deepening the trade deficit and fueling imported inflation. Thus, depreciation will worsen the trade balance, a classic case of the J-curve effect – Economics 101.

In the medium term (FY 26-27), Bangladesh and India could capture Pakistan’s U.S. market share with lower energy tariffs and competitive pricing. Even if tariffs on Pakistani exports are later removed, the damage to export competitiveness could be lasting.

With that, as U.S. buyers shift to cheaper alternatives, investor confidence will weaken, reducing foreign direct investment in manufacturing and exports.

The fallout goes even further. In the long term (FY 28 & beyond), structural damage to Pakistan’s export sector is inevitable if alternative markets and policy reforms are not pursued. A persistently low export base amid trade restrictions will not only stall economic growth but also increase reliance on IMF bailouts. Worse still, a weaker rupee will make external debt repayments more expensive, leading to higher borrowing costs – all while dollar inflows remain insufficient due to declining exports.

Trade Deficit Projection: How Bad Can It Get?

Pakistan’s trade deficit is growing at 3% per month. Without additional tariffs, it could reach USD 25 billion or as high as 27.8 billion by FY25. A 20% tariff hike would worsen the deficit, triggering long-term ripple effects – an outcome Pakistan must avoid in the current global environment.

If imposed, these tariffs would immediately hit Pakistan’s USD 6 billion exports to the U.S., exacerbating the trade deficit and impacting employment, particularly in textiles.

A way forward:

To protect its exports, the government must:

  1. Proactively negotiate a Preferential Trade Agreement with the U.S. that allows duty-free cotton imports from the U.S. to be used in value-added textile manufacturing bound for the U.S. market. We have seen such an arrangement under Caribbean Basin Trade Partnership Act (CBTPA), where apparel assembled in the Caribbean and Central America using U.S.-origin fabrics, yarns, and threads entered the U.S. duty-free.

While some may question the timeliness of such a deal, India is set to begin FTA negotiations with the U.S. this month despite tariff tensions. Pakistan cannot afford the economic fallout of a tariff war and must urgently pursue a trade agreement to secure long-term export growth and economic stability.

  1. Restore the zero-rating/sales tax exemption on local supplies for export manufacturing under the EFS to prevent industry closures, especially as global trade becomes increasingly protectionist.
  2. Reduce energy costs for textile manufacturers by bringing tariffs in line with competing economies to maintain cost competitiveness, ensuring exports remain viable even in the face of an exogenous shock.
  3. Diversify export markets by expanding trade with Europe, Central Asia, and Africa, reducing overreliance on a single market and ensuring long-term market stability.

With structural challenges weighing on Pakistan’s economy, rising imports, soaring energy costs, and tariff uncertainty are threatening its export-led growth.

The path is clear and evident – secure a U.S. trade agreement, reverse harmful tax policies, and ensure competitive energy pricing. Inaction will further imperil Pakistan’s global trade position and entrench economic instability for years to come.


image_1752126736495.webp

March 3, 2025

Export-led growth is the mantra these days, but government seems uninterested in actually facilitating it.

The Export Facilitation Scheme was a well-designed initiative that allowed exporters access to zero-rated inputs—i.e., duty-free and sales tax-free—be it imported or local, as well as zero-rated transfers of materials between EFS bond holders.

However, in the FY25 budget, the government inexplicably withdrew the sales tax exemption on local supplies for export manufacturing while imports of the same remain duty-free and sales tax-free. As a result, exporters procuring domestically manufactured inputs must now pay 18% sales tax. Although refundable in principle, only around 60-70% of the refund is issued after delays of over 6 months, as the FASTER system that promised automated refunds within 72 hours has been made dysfunctional. The remaining amounts are indefinitely deferred for manual processing with no progress on these refunds over the last 4 to 5 years.

This further adds an additional administrative and time cost of 6-10 months from the purchase of inputs to the export of manufactured goods when sales tax refunds can be claimed—a burden that imports do not face.

All else equal, this policy effectively provides foreign industry and agriculture an 18-30% advantage over local industry and farmers.

The Federal Board of Revenue’s offers three main justifications for withdrawing the sales tax exemption on local supplies: that the sales tax is refundable in any case, that exemptions break the “value chain” in the value added tax regime and limits the tax authorities’ visibility over it, and that there were significant pilferage and leakages in the system.

he first argument—that sales tax is refundable—would have merit if the refund system actually worked. Rule 39F of the Sales Tax Rules 2006 mandates that refunds be processed within 72 hours, yet the system is fundamentally broken, and the FBR has shown no intention of fixing it. As of FY24, over Rs. 180 billion of the textile sector’s liquidity was stuck in sales tax refunds alone. Beyond this, the government also owes the textile sector Rs. 25 billion in unpaid duty drawbacks, Rs. 100 billion in pending income tax refunds, Rs. 35.5 billion in outstanding DLTL/DDT dues, Rs. 4.5 billion in pending TUF payments, Rs. 3.5 billion in unpaid markup subsidies, and Rs. 1 billion in outstanding RCET differential payments. This reflects a broader pattern of the government bring addicted to private sector liquidity to manage its own distraught cash flows.

If the intention is to refund the sales tax, then why charge it in the first place?

The second argument—that zero-rating local supplies disrupts the VAT chain—is, at best, a procedural data issue that the FBR should be able to manage given its grand digitalization ambitions. Under a VAT system, each stage of the supply chain pays tax on its value addition while claiming refunds on previously paid tax, ensuring that only the final consumer bears the cost. The FBR contends that exempting local supplies under EFS removes a stage of taxation, disrupting revenue tracking and enforcement. However, this issue is entirely solvable through proper documentation, as suppliers would still report transactions under EFS without charging sales tax, allowing the FBR to maintain oversight. If the system can handle tax-free imports under EFS, it can certainly apply the same controls to local supplies.

In fact, many countries operating under a VAT regime have successfully implemented zero-rated regimes for export-oriented industries:

Country Year Overview
Bangladesh 1991 The VAT Act, 1991 allows zero-rating on local inputs for export-oriented industries, mainly in textiles and RMG. Domestic suppliers to exporters do not charge VAT.
India 2017 Under GST Law (2017), exporters can procure local inputs tax-free using a Letter of Undertaking (LUT), reducing reliance on imports.
European Union 2006 The EU VAT Directive (2006/112/EC) provides zero-rating on goods supplied for export, with strict documentation requirements.
Turkey 1985 VAT Law No. 3065 exempts local sales to exporters from VAT, strengthening domestic cotton & textile supply chains.
Uzbekistan 2020 Reforms in Tax Code allow zero-rating on local cotton sales to textile mills, shifting the country from raw cotton exports to value-added textiles.
Egypt 2016 Under VAT Law 67 (2016), cotton and textile inputs for exporters are zero-rated, improving cash flow and local demand for Egyptian cotton.
Brazil 2004 The Special Regime for Textile Industry enables local cotton sales to be VAT-exempt for textile mills and exporters, reducing reliance on imported fiber.
Malaysia 2018 The Sales & Service Tax (SST) system allows zero VAT on domestic raw material sales for export-oriented manufacturing industries.
South Africa 1991 The VAT Act (1991) exempts domestic supplies linked to exports, particularly in mining, agriculture, and textiles, provided documentation is maintained.

The third argument—pilferage—is the weakest of all, as the bulk of leakages in EFS occurred on the import side, yet imports remain duty-free and sales tax-free. In fact, the tax disparity between local and imported inputs has worsened the issue. The primary avenue for abuse is when exporters import zero-rated inputs but use them for merchandise sold in the domestic market while exporting goods made from locally procured inputs instead. However, proposed amendments to the EFS framework—such as reducing the reconciliation period from five years to nine months and strengthening audits—are sufficient to curb such practices.

When all other justifications fall apart, the bureaucracy falls back to its favourite recourse: blame the IMF. But let’s be clear: the IMF does not dictate specific policy measures to governments. It negotiates policy conditions with governments seeking financial assistance, with Finance Minister and Governor State Bank proposing policy changes through the Memorandum of Economic and Financial Policies. While the IMF pushes for broader objectives like higher revenue collection, specific measures to achieve these objectives are determined by the government. In this case as well, the government itself chose to impose sales tax on local inputs while maintaining duty-free and tax-free imports, expecting to generate Rs. 7-8 billion in revenue from what is essentially a revenue-neutral policy. It is the government’s responsibility to support local industry and protect livelihoods—something the IMF, a lender at the end of the day, has no stake in.

If today the government finds itself in a weak negotiating position with the IMF, it is entirely due to the shenanigans of the bureaucracy that has been handling these negotiations across 24 separate programs since 1959. And despite all the experience they have gained, they continue to miss key quantitative targets like revenue collection, while failing to meet structural benchmarks such as the privatization of a national airline that drains over Rs. 100 billion annually. Why should the private sector and the people of Pakistan bear the cost of their repeated failures? Will anyone ever be held accountable for the billions of dollars lost and the millions of livelihoods damaged by these policy decisions?

There is now broad consensus that the withdrawal of sales tax exemptions on local inputs was a blunder, especially for upstream segments of the textile sector, and that a level playing field must be restored. There are two ways to achieve this: one option is to impose the same 18% sales tax on EFS imports, but this would only level the playing field by subjecting imports to the same refund delays and liquidity issues plaguing local suppliers and ultimately increase costs for exporters.

A far better alternative, preferred by all stakeholders, is to restore the Export Facilitation Scheme to its pre-FY25 form, reinstating the zero-rating and sales tax exemption for local supplies. This is the only viable path if the government is truly committed to export-led growth. In fact, the scheme should be expanded beyond a single stage to include multiple stages of the value chain, maximizing the benefits of zero-rating.

Pakistan is one of the few countries with a fully developed textile value chain, yet the government’s missteps have broken it. A surge in yarn imports have displaced the local spinning sector. Ironically, it includes from Uzbekistan—a country that modelled its own textile value chain reforms on Pakistan’s example and even extended zero-rating to cotton sales for yarn manufacturing, strengthening its domestic industry while Pakistan’s spinning sector collapses.

Sustained economic growth requires not just higher exports but greater value addition in those exports. A country can either import $3 worth of inputs and add $2 of value or capture the full $5 within its own supply chain. The latter approach keeps capital circulating within the domestic economy, creating multiplier effects in income generation and tax collection. While shifting to a final consumer goods export model may yield higher absolute value, it results in lower domestic value addition and foregoes these economic benefits. More critically, Pakistan lacks the productive capacity and investment climate needed to sustain such a shift.

The sales tax disparity also discourages the long-term development of export-oriented sectors through backward and forward linkages. Given that Pakistan’s business environment is already burdened by high costs—whether in electricity, gas, taxation, or the overall cost of doing business—it is unrealistic to expect local suppliers to compete on an unequal footing with duty-free and tax-free imports.

Pakistan urgently needs a strong, labour-intensive manufacturing base to capitalize on its large and growing workforce. The idea that a country of 250 million people will escape economic stagnation through $10 billion in IT exports is wishful thinking. If the government is serious about economic revival and export growth, it must fix the Export Facilitation Scheme and ensure a fair, competitive landscape for local industry.


image_1752123720635.webp

February 19, 2025

With an IMF determined to punish past misdemeanours and a government unwilling to embrace meaningful reform, Pakistan’s gas sector is as good as finished and will take industry down with it.

For over three decades, the government actively promoted industrial captive power generation, yet as energy sector mismanagement has resulted in surplus power capacity and escalating tariffs, captive power producers (CPPs) have been made the scapegoat. As the power sector crisis deepened, CPPs were blamed. Under the 2024 Stand-By Arrangement (SBA), the government proposed eliminating CPPs’ gas usage and forcing them onto the national grid to address stranded power capacity. However, this policy—developed without adequate analysis—risks destabilizing both the gas and industrial sectors, with broader economic repercussions. After months of uncertainty regarding gas supply for captive power, the government has opted not to cut off supply but has instead hiked the captive gas tariff to Rs. 3,500/MMBtu plus an additional “grid transition levy” to force industrial energy demand to the grid.

Energy pricing in Pakistan lacks any coherent market-driven logic. Power and gas tariffs are set based on arbitrary calculations that balance the government’s books—even then to the extend possible—rather than reflecting economic realities or ensuring efficient resource allocation. The grid transition levy is the latest in a series of such ill-conceived interventions.

Its stated goal is to align the cost of gas-fired captive generation with the B3 grid tariff, removing any cost advantage for captive power. Yet even the Ordinance through which it has been implemented is unclear about the mechanism with which to achieve this. It first directs authorities to calculate the levy by comparing industrial B3 tariffs with captive power costs, only to contradict itself by mandating automatic rate hikes—5% immediately, increasing to 20% by August 2026.

These conflicting approaches expose the policy’s lack of foresight. If the intent is to eliminate the cost advantage of captive power, then the appropriate mechanism would be a benchmark tariff applied across the board rather than a levy, given that captive consumers can currently avail gas through the utilities at Rs. 3,500/MMBtu or through third-party access at mutually negotiated rates.

Given the variation in effective prices faced by consumers, for the levy to achieve its objective it needs to be tailored to each consumer’s effective gas price. Moreover, for third-party access consumers, economic logic suggests that shippers would simply adjust prices to match the benchmark, capturing the levy as profit rather than achieving the intended policy outcome. This is a textbook case of market distortion, where intervention begets more intervention, ultimately failing to achieve its objective.

Beyond pricing, the assumption that captive consumers can seamlessly transition to the grid is deeply flawed. Grid inefficiencies, infrastructure limitations, and supply reliability remain major concerns. Captive plants operate at different efficiencies based on gas quality and operational conditions, yet the levy applies a blanket cost increase.

The most efficient plants will be penalized, while inefficient operations on the national grid are effectively rewarded.

While the Power Division has directed DISCOs and K-Electric to sign service level agreements (SLAs) with industrial consumers that include penalties for non-compliance, the very need for such agreements raises fundamental concerns. Shouldn’t the national grid inherently provide reliable, high-quality power to all consumers without requiring formal assurances? The fact that DISCOs are now pledging improved supply through SLAs is, in itself, an admission that the existing grid power supply is inadequate for industrial consumers.

Moreover, the SLA clause mandating consumers to source at least 70% of their energy consumption from the grid is highly problematic. Globally, industrial consumers integrate multiple energy sources—including solar, wind, furnace oil, coal, and gas-fired captive power generation—to optimize costs and ensure energy security. There is no regulatory restriction in Pakistan preventing such integration, and this requirement contradicts international best practices. It also severely impacts export-oriented industries, which are increasingly under pressure to meet sustainability commitments and transition towards carbon neutrality. While Pakistan benefits from significant hydropower capacity, the overall carbon footprint of grid electricity remains high due to the intermittency of renewables and continued reliance on thermal generation. Restricting industrial consumers’ ability to diversify energy sources not only undermines their environmental objectives but also weakens their global competitiveness.

Additionally, the cost implications of this requirement are severe. Forcing consumers to rely predominantly on an expensive grid deprives them of the opportunity to optimize costs through alternative, more affordable energy sources. Moreover, fines imposed on DISCOs for SLA violations offer little incentive for genuine compliance, as the financial burden inevitably circles back to consumers—further exacerbating already prohibitive power tariffs.

Adding to the absurdity is the claim that the levy’s revenue will be used to lower power tariffs. Even at Rs. 3,500/MMBtu, captive power generation is already more expensive than the January 2024 B3 grid tariff of ~13 cents/kWh even for the most efficient generators:


Gas consumption has plummeted, as reflected in declining Sui line pack reports, but whether grid consumption increases correspondingly increase remains to be seen. Alternative fuel sources such as furnace oil or coal-fired captive power remain cheaper than grid electricity, further undermining the policy’s effectiveness and making any significant revenue generation from the levy highly questionable.

Rather than introducing arbitrary levies and counterproductive administrative controls, the government should embrace a market-based approach. Textile industries, for instance, have consistently stated their willingness to pay full RLNG rates for self-generation. Yet, instead of allowing industries to procure gas at international prices, the government supplies the same to other consumers at highly subsidized rates, contributing to a Rs. 3 trillion gas circular debt. Pricing out the highest-paying consumers will only lead to exacerbation of the circular debt, billions in lost exports and millions of job losses.

The core issue is that true market reforms would expose the fragile economic equilibrium the government has built through administrative and price controls, and cross-subsidies—not just in energy, but across taxation and industrial policy as well.

Consider the Export Facilitation Scheme, which is actively discouraging domestic value addition in exports while promoting imports. Since July 2024, imported raw materials have been duty- and sales-tax-exempt under EFS, while locally produced inputs are subject to an 18% sales tax. If an exporter purchases local supplies, they must first pay 18% sales tax, then wait six to ten months to file for a refund, only to receive a partial reimbursement of about 70% after a delay of over 6 months, while the remaining 30% remains indefinitely stuck in a broken manual processing system that has seen no progress for years.

Despite universal acknowledgment of the distortionary impact of this policy, the government has refused to correct it. The result has been catastrophic: over 100 spinning units—representing 40% of Pakistan’s production capacity—have already shut down, with the remainder teetering on the brink of insolvency. If unaddressed, this crisis will inevitably spread further downstream to weaving, processing, and garment manufacturing, if energy prices don’t kill them first.

The government must decide whether it genuinely supports economic reform or if it intends to persist with the status quo. If it is serious about reform, it must embrace a market-driven approach—starting with the energy sector.

The grid transition levy must be abandoned, and the gas market must be fully opened, allowing industries to procure gas through third-party access or import their own LNG, free from government-imposed price distortions. The role of the Sui companies in upstream gas allocation should be phased out, restricting them to the gas transportation business only while allowing private-sector players to take over supply.

Beyond gas sector reform, Pakistan must also move towards liberalization of the power sector by operationalizing the Competitive Trading Bilateral Contract Market (CTBCM) that would allow industries to procure competitively priced electricity through B2B contracts. However, for CTBCM to succeed, it must have a rational and transparent wheeling charge of 1 to 1.5 cents/kWh, excluding cross subsidies and stranded costs of the grid, to ensure that industrial consumers are not burdened with extraneous costs unrelated to their actual consumption. A well-functioning power market will improve efficiency, encourage competition, and provide industries with reliable and cost-effective electricity, removing one of the biggest constraints to economic growth.

This would also enable industries access to clean and green electricity that is an increasing necessity for maintaining global competitiveness under upcoming international trade regulations, such as the EU’s Carbon Border Adjustment Mechanism (C-BAM) and existing net zero commitments that require exporters to demonstrate low carbon emissions during production.

If the government is serious about industrial growth, opening up of energy markets is the only way forward. Pakistan’s economy cannot afford half-measures. The continued reliance on flawed interventions will only deepen the crisis. The choice is clear: let the market decide.


image_1753073243528-1280x853.webp

February 14, 2025

By Shahid Sattar | Sarah Javaid
As the EU tightens its regulations, many countries view compliance as a mere obligation, but the implications of this can have benefits far beyond maintaining trade relations. By aligning with sustainability standards, Pakistan can unlock access to global value chains, drive export-led growth, and tackle long-standing inefficiencies in the industrial value chain, including under-reporting, sales tax evasion, and the misuse of EFS.

With the EU accounting for 30% of Pakistan’s total exports, any regulatory shift from the EU will inevitably impact Pakistan’s trade. Rather than viewing this as a challenge, the policy makers need to turn this into an opportunity. While Pakistan has made progress under the GSP+ since 2014, continued access to the EU market will now depend upon compliance with their emerging regulations.

One such framework is the Digital Product Passport (DPP) under the Eco-design for Sustainable Products Regulation (ESPR), which was introduced in mid-2023 and will be enforced from 2027 onwards in sectors such as textiles, metals, and batteries. As the name suggests, the DPP represents a digital transformation in the industry’s value chain, enhancing transparency by digitally documenting product origins and production processes. It ensures due diligence in human rights and environmental standards across the value chain, preventing any product from qualifying for export without meeting transparency requirements. These requirements will be verified through a QR code displaying key production details, hence making the DPP a mandatory requirement for exporting to the EU.

But there’s more to it. Beyond ensuring due diligence, digitization through the DPP offers a real-time solution to perennial issues like under-invoicing, under-reporting, and EFS misuse. Pakistan must recognize this as a strategic advantage. Greater transparency will not only enhance access to global markets but also reinforce tax compliance.

Why Digitizing the Value Chain through DPP is Imperative?

Since 2013, Pakistan’s exports to the EU have grown significantly, with total exports increasing by 76% and textile exports by 87%. However, as buyers now prioritize transparency and traceability, the DPP is no longer just a compliance requirement – it is a binding regulatory necessity for maintaining and expanding Pakistan’s presence in the EU market.

Given this shift, it is crucial to recognize the link between the DPP and its potential role in addressing Pakistan’s structural challenges.

The FBR has long sought to curb tax evasion through initiatives like the Track and Trace System (TTS), but its limited scope has failed to eliminate illicit practices in many sectors such as tobacco and cement. True value chain traceability requires a broader approach – one that ensures due diligence while tackling tax fraud.

Pakistan’s textile sector remains highly fragmented, with SMEs constituting a significant portion of the value chain, primarily operating at the ginning and spinning stages. Many SMEs either supply large exporters or cater to the domestic market, but the lack of integration across the textile value chain leaves multiple supply channels vulnerable to tax evasion.

Following the FY 2025 budget’s removal of the sales tax exemption on local supplies for exports under the EFS, exporters increasingly turned to duty-free and sales tax-free imported yarn, which was comparatively cheaper. This shift away from sourcing domestic inputs – such as yarn from SMEs – combined with the EU’s strict traceability requirements, has made identifying the origins of imported yarn critical. Any product containing yarn that directly or indirectly originates from Xinjiang (Uighur region) faces an EU ban, jeopardizing not only exports but also brand credibility and future trade policies.

Despite these concerns, gaps in monitoring imported yarn usage persist. Many manufacturers misuse the EFS by diverting duty-free inputs to local production instead of exports, distorting the local yarn and cotton market. In parallel with the illegal use of this policy, 40% of SME spinning units have shut down due to the influx of imported inputs, further impacting local farmers who are left without buyers for their cotton.

At the farming stage, a significant number of unregistered cotton farmers in Pakistan operate within an informal market, relying heavily on uncertified seeds. This has led to poor cotton yields, increasing Pakistan’s dependence on high-value cotton imports from the US and Brazil.

Another major challenge requiring DPP’s digital intervention is the widespread tax evasion in cotton trading, commonly referred to as “Golmaal.” Approximately 2 million cotton bales are under-reported annually to evade sales tax. Estimates suggest that in FY 2024 alone, PKR 32.8 billion in sales tax was lost due to Golmaal cotton bales and banola, perpetuating tax evasion across the value chain.

Given these deep-rooted challenges, implementing the DPP is a fundamental prerequisite. A robust digital traceability system will ensure compliance, curb tax evasion, eliminate Golmaal practices, and expose corruption under the EFS.

Strategic Use of DPP and Role of FBR:

The implementation of this system requires urgent action from the FBR, starting with the creation of a centralized database shared with relevant ministries, such as the Ministry of Commerce. All players in the textile value chain must register and integrate into the system to qualify for exports to the EU. The final product will carry a QR-coded DPP, containing compliance details from farm to finished garment.

To begin with the first tier of the value chain, unregistered farmers will need to register once the DPP is implemented. Mandatory registration will enhance traceability and boost cotton productivity by curbing the use of fake seeds, documenting farmers’ produce, and streamlining underreported production.

To track Golmaal cotton bales, RFID (Radio Frequency Identification) technology can assign unique group IDs for real-time monitoring from the field to ginning, storage, and shipping, all linked to the centralized database. Similarly, QR codes on yarn, fabric, and finished products will trace raw material origins – whether imported or domestic – while also verifying compliance with sustainability standards, including water and energy usage, as well as any form of forced labor practices. Transaction records documenting manufacturers, suppliers, and buyers will ensure full value chain visibility.

With real-time digital records, the FBR can monitor value addition at each stage, significantly reducing tax evasion. Value addition currently stands at 5% in ginning, 10% in spinning, 15% in weaving/knitting, 20% in finishing, and 50% in garment manufacturing. The DPP will make this data transparent for policymakers. Linking it to POS-based tax collection will automate tax calculations, eliminating underreporting, fake invoicing, and ghost transactions, while also reducing manual intervention in tax collection.

Preventing the misuse of EFS through automation:

As discussed, the EFS has caused two major distortions in the textile value chain: the misuse of duty-free imports in local manufacturing and the challenge of tracing imported yarn origins. These issues undermine the system’s purpose and demand immediate intervention.

As of 2024, EFS supports over 1,700 exporters, who must submit an annual reconciliation statement within 30 days of the fiscal year’s end, with audits every five years. The previous five-year retention period for duty-free imports – now reduced to nine months – enabled large-scale misuse, with imports meant for exports diverted to local manufacturing to evade taxes.

Consequently, concerns arise over the origins of imported inputs, putting supply chain credibility at stake.

Ensuring export compliance with the EU now hinges on tracing imported yarn – its cotton source, production process, and adherence to sustainability standards. The DPP will strengthen oversight by digitally linking each imported input under EFS to its final exported product, preventing misuse and guaranteeing compliance.

By integrating DNA testing and digital verification, imported yarn and fabric can be tested at entry points and assigned a QR code verifying their origin. These records will be matched with final products to ensure compliance with EU regulations and prevent EFS misuse.

This system will ensure exporters use duty-free inputs within the nine-month retention period, eliminating misdeclaration and diversion. Failure to reconcile input usage with output will result in penalties or EFS revocation by the FBR.

Additionally, sales tax collection will be automated, ensuring that tax refunds under zero-rated regimes like EFS are granted only to genuine exporters.

Urgent call for making traceability mandatory in Pakistan:

To make this digital transformation happen, the government needs to urgently step up.

Past experiences demonstrate that without a legally binding system, the desired outcome will remain elusive. Therefore, the NCC must be designated as the sole regulatory body for exporters’ compliance.

A centralized database integrated with the NCC will enable it to oversee compliance with sustainability standards across the value chain and issue DPPs (in the form of QR codes) to textile exporters, allowing European buyers to access due diligence details directly from the final product.

Exporters who fail to provide the required information will not receive a DPP and, consequently, will be unable to export.

This will ensure exporters cooperate in data sharing and adhere to tax regulations. Non-compliance should result in penalties, including the revocation of EFS benefits.

Urgent attention is needed to designate the NCC as the regulatory authority and make the DPP a mandatory requirement. This will not only give Pakistan a first-mover advantage in South Asia but also enhance tax management, ensuring the country stays ahead in both sustainability and fiscal discipline.


LOCATIONS

Where We Are


GET IN TOUCH

Follow Our Activity


IslamabadKarachiLahore